FHA and 203k Loans for an ADU
FHA financing is built for owner occupants, and it reaches ADUs in two ways. A standard FHA loan can buy a home that already has one. An FHA 203k renovation loan can roll the cost of some conversions, such as a garage or basement, into the mortgage itself.
- We explain every option, not just one product
- Matched with lenders who finance ADUs
- No obligation to take any offer
How FHA financing works for an ADU
The home must be your primary residence. Within that rule, there are two routes.
Buying a home with an existing ADU works through a standard FHA purchase loan. FHA guidance has been updated so that, in certain cases, some rental income from the ADU can count toward qualifying. Your lender decides whether your situation fits.
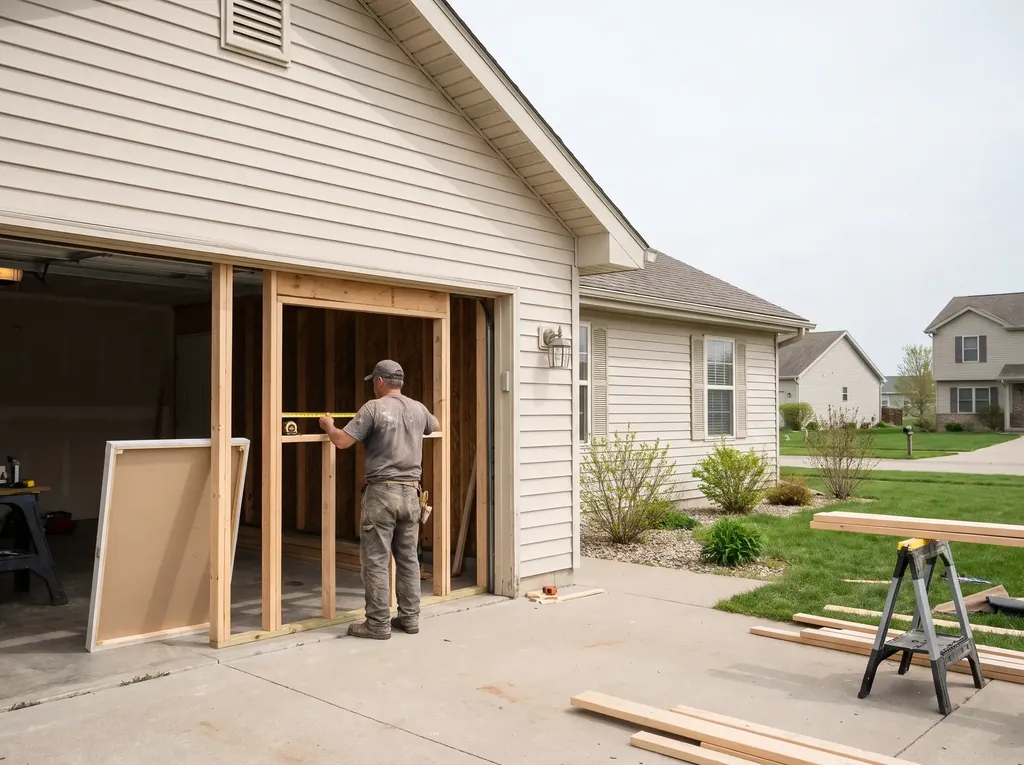
Adding an ADU usually means a 203k loan. It lends on the value of the home after the work is done and pays a contractor as the project moves forward. It can fund some conversions of existing space. Whether it covers a new detached unit depends on the lender, so ask a 203k lender directly before you plan around it.
At a glance
- Best for: owner occupants buying, or converting existing space
- How money arrives: at closing for a purchase, in stages for a 203k
- Occupancy: the home must be your primary residence
- What lenders check: credit, income, the property and the renovation plan
FHA loan pros and cons for an ADU
Pros
- Built for buyers with smaller savings or thinner credit
- A 203k lends on the value after the work is done
- One loan can cover the home and the conversion
- Some ADU rent may help you qualify
Cons
- Primary residence required
- Detached new builds may not qualify under a 203k
- Mortgage insurance adds to the cost
- Fewer lenders handle 203k loans well
When another loan fits better
If your project is a detached new build, an ADU construction loan is designed for it. If you are converting a garage, compare the costs and loan options for that project size. If rent from the unit is central to your plan, learn how lenders count ADU rental income.
ADU construction loans
Paid to your builder in draws as the unit goes up, then converted or refinanced.
Garage conversion ADU financing
Costs and loan fit for the smallest ADU projects.
Using ADU rental income to qualify
When lenders can count future rent from the unit.
FHA loan for an ADU questions
What is the cheapest option for an ADU?
Converting space you already have, such as a garage, usually costs less to build than a detached unit. For FHA borrowers, that is also the type of project a 203k loan is most likely to cover.
Can I use an FHA 203k loan to build an ADU?
A 203k can fund some conversions of existing space. Whether a detached new build qualifies depends on the program rules and the lender, so ask a 203k lender before you commit to a design.
Can FHA count rental income from an ADU?
In certain cases, yes. Updated FHA guidance allows some ADU rental income to count toward qualifying. Expect the lender to ask for proof of the rent, and to apply its own limits.
Talk to a lender who finances ADUs
Tell us whether you are buying or converting, plus your rough budget and timeline. We will connect you with a lender who handles FHA and 203k loans so you can compare real terms.
Talk to a specialist: (555) 555-0141
Thanks. We have your details and a lender who finances ADUs will be in touch, usually within one business day.